If you’ve tried to keep up with Washington’s estate tax lately, I don’t blame you for giving up. The rules changed in July 2025, then changed again in July 2026.
Here’s where things stand now. For deaths on or after July 1, 2026, Washington taxes estates above $3 million, with rates back to the older range of 10 to 20 percent. That $3 million line is now effectively frozen. And for a lot of ordinary Seattle families, that’s closer than it sounds.
Washington Estate Tax in 2026: What Changed on July 1
Washington is one of the few states with its own estate tax, and it kicks in far below the federal level. In 2026 the federal exemption is $15 million per person. Washington’s is $3 million. So plenty of families who will never owe a cent of federal estate tax can still owe Washington.
Three Rule Sets in Two Years, Explained Simply
Here’s the timeline.
- Before July 1, 2025, the Washington exclusion was $2.193 million and had been stuck there since 2018. Rates ran from 10 percent up to 20 percent on the largest estates.
- From July 1, 2025 through June 30, 2026, the Legislature raised the exclusion to $3 million, then it adjusted up to $3.076 million in January 2026. But it also raised the rates sharply, with a new top rate of 35 percent.
- Starting July 1, 2026, a new law, Senate Bill 6347, rolled the rates back to the earlier 10 to 20 percent schedule. It also reset the exclusion to $3 million.
To put the rate change in perspective, Beresford Booth, a Washington law firm, ran the numbers on an $8 million estate. Under the July 2025 to June 2026 rates, the Washington tax came to about $840,000. Under the rates in effect from July 2026, it drops to about $730,000. That’s real money, but notice what didn’t change: both estates still owe a large bill, because both are well over the $3 million line.

Which set applies depends on the date of death, not the date the will was signed. That matters for anyone handling an estate right now, and it matters for anyone whose plan was built around one particular year’s rules.
Why the $3 Million Exclusion Is Now Frozen
The new law ties future inflation adjustments to a regional price index that no longer exists. In practice, that means the $3 million exclusion isn’t going to grow on its own. Some estate planners expect lawmakers to revisit this in 2027, but nobody can promise that.
Think about what that means in Seattle. Home values tend to climb. Retirement accounts grow. The line stays put. Every year a frozen exclusion stays in place, more middle class families drift toward it without changing anything about how they live.
Will Your Seattle Family Owe Washington Estate Tax?
Let’s look at an ordinary picture.
How a West Seattle House and Retirement Accounts Add Up
Picture a retired couple in West Seattle. They bought their house decades ago, and it’s worth well over a million dollars today. They each have retirement accounts. There’s a modest brokerage account, a car, and some savings.
Nobody would call them rich. But add it up and they can be surprisingly close to $3 million. And here’s the part couples often miss. Washington doesn’t let a surviving spouse automatically use the unused exclusion of the spouse who died first. Under federal law that’s possible. Under Washington law it isn’t. So without planning, a couple can end up using only one $3 million exclusion instead of two.
Here’s how that plays out. Say the first spouse dies and leaves everything outright to the survivor. No tax is due then, because property passing to a spouse is generally deductible. But when the survivor dies years later, the whole combined estate is taxed with only one $3 million exclusion. Half the couple’s tax protection simply disappeared.
That’s the kind of thing a well drafted plan can address. A plan that just says “everything to my spouse” may waste the first spouse’s exclusion entirely.
Life Insurance and Other Assets People Forget to Count
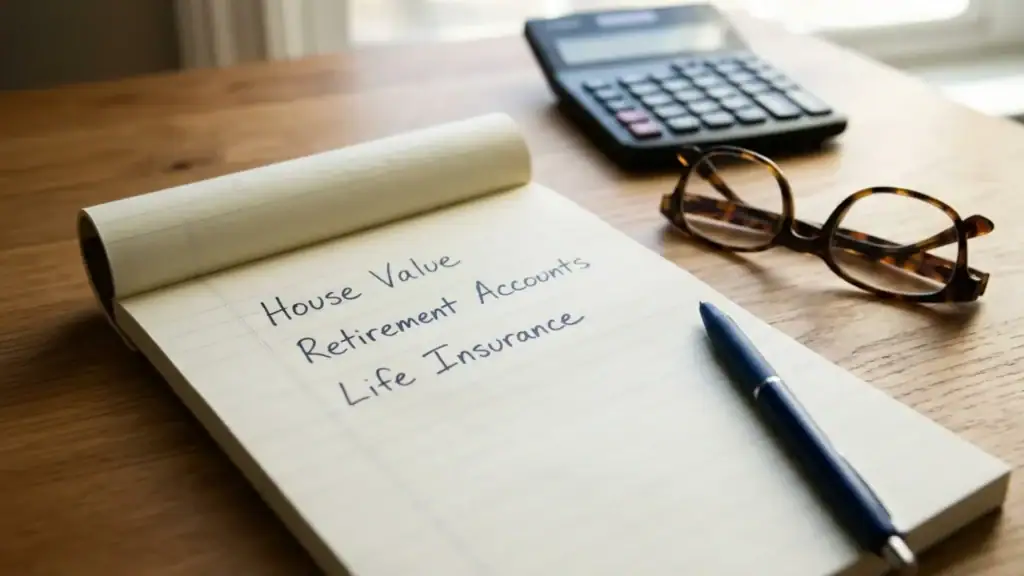
When people estimate their estate, they usually count the house and the bank accounts and stop. But the Washington taxable estate is calculated a lot like the federal one, which means more things count than people expect.
Life insurance you own on your own life generally counts at its death benefit, not its cash value. A $1 million term policy you barely think about can push an estate over the line by itself.
Retirement accounts count at their full value, even though your kids will owe income tax when they withdraw the money later.
Your share of a business, rental property or vacation cabin counts too, and those can be hard to value.
If you’ve never added all of this up on one page, it’s worth doing. Honestly, the number surprises people more often than not.
There’s one bit of good news hidden in Washington’s rules. Washington doesn’t have its own gift tax. That means money or property you give away during your life generally isn’t part of your Washington estate when you die, as long as it’s really given away. For some families, steady gifts to children or grandchildren over several years can bring an estate back under the line. It’s not right for everyone. You don’t want to give away money you might need for care later. But it’s a tool a lot of people don’t know they have.
And if you’re married, there’s a newer rule worth knowing. Since January 2025, a married person’s home can be left out when deciding whether a Washington estate tax return even needs to be filed after the first spouse dies. That helps with paperwork. It doesn’t remove the home from the estate for tax purposes later, so don’t read it as a loophole.
Signs Your Washington Will or Trust Needs an Update
Not every plan needs to change because of SB 6347. But some definitely do. Here’s what I’d look for.
Formula Clauses Written for Old Exemption Amounts
Many trusts and wills don’t name a dollar amount. Instead they use a formula, something like “the maximum amount that can pass free of estate tax goes into this trust, and the rest goes to my spouse”. That sounds smart, and it often is. But when the exemption amount jumps or freezes, the formula can push more or less money into a trust than you intended.
If your plan includes a credit shelter trust, a bypass trust, or a disclaimer trust, it was probably built around a specific set of tax rules. With three rule sets in two years, it’s worth checking that the formula still does what you want under the current one.
Plans Signed Before 2025 and Married Couple Planning
If your plan was signed before 2025, it was written for the old $2.193 million world, before any of these changes. It may still work. It may also be doing a lot of unnecessary work, or not enough.
For married couples, the frozen exclusion and the lack of spousal sharing are the two big issues. How your property is titled, whether it’s community property or separate property, and who’s named on beneficiary forms all affect how much of each spouse’s exclusion actually gets used.
Here’s a quick test. Pull out your plan and look for the words “credit shelter,” “bypass,” “exemption equivalent,” or “maximum amount that can pass free of tax.” If you find any of them, that’s a plan worth having someone check against the current law. If you can’t find your plan at all, that’s an even stronger reason.
And it’s not just tax. Life has probably changed too. New grandkids, a child who’s struggling, a second marriage, a house that’s now worth far more. If you’re also wondering whether your family would face probate at all, my post on when a Seattle estate actually requires a probate lawyer covers that side.
The Rates Dropped, but the $3 Million Line Stopped Moving
Here’s the thing about Washington’s estate tax right now. The rates went down, which is good news. But the line stopped moving, and that’s the part that will quietly catch families over the next few years. You don’t need to panic or rebuild everything. You just need to know two numbers: roughly what your estate is worth today, and what your current plan actually does with it. Once those are on the same page, it’s usually obvious whether you need a small adjustment, a bigger update, or nothing at all. That’s a conversation worth having before the next law change, not after.
If you live in Seattle, West Seattle, Burien or anywhere nearby and want to know where your plan stands, contact me or call 253-424-4750. Bring your current will or trust and a rough list of what you own. I’ll tell you plainly whether it needs to change. In most cases the first consultation costs little or nothing. You can read more about my probate and estate law practice here.