Slipped on an Icy Sidewalk in Seattle? Who Pays: the Property Owner or the City
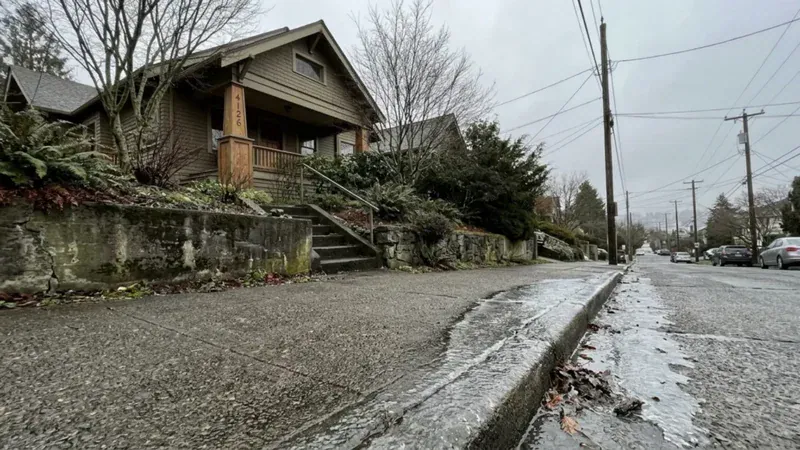
You were heading downhill to the bus, the sidewalk looked wet, and a second later you were on your back staring at the sky. Now your wrist is in a brace and you’re wondering if anyone is actually responsible. In Seattle, the owner or occupant of the property next to the sidewalk is usually the one responsible for clearing snow and ice, not the city. But where you fell, and how long that ice sat there, changes everything. Who Is Responsible for Icy Sidewalks in Seattle Under City Law? Most people I talk to assume the city is on the hook. The sidewalk is public, right? It sits in the city’s right of way. So it feels obvious that the city should pay when it turns into a skating rink. Seattle doesn’t see it that way. Why Seattle Puts Sidewalk Ice on the Property Owner, Not the City Seattle Municipal Code 15.48.010 says the owner or occupant of private property has to remove snow and ice from the sidewalk next to their property in a timely manner. The code also asks them to keep it from becoming icy, ridged or uneven in a way that’s hazardous to people walking by. So the city owns the concrete, but the neighbor owns the job of clearing it. That doesn’t mean every fall in front of a house is automatically the owner’s fault. Washington law still asks a basic question: did the owner know, or should they have known, about the ice, and did they have a reasonable chance to deal with it? If you fell at 7 a.m. after snow stopped at 5 a.m., that’s a hard case. If the same frozen ridge had been sitting there for three days while the owner drove past it twice a day, that’s a very different conversation. Timing is the whole case. Honestly, it’s the first thing I ask about. When the City of Seattle Can Still Share the Blame The city isn’t off the hook everywhere. There are spots with no neighbor next door to blame: curb ramps at intersections, bus stops, public stairways, and paths through city parks. The city can also be responsible when the problem isn’t just weather. Think of a broken drain that keeps flooding the same stretch of sidewalk, which then freezes every cold night. To hold the city responsible, you generally have to show it knew about the hazard, or should have known, and didn’t act reasonably. That’s harder to prove than most people expect. And sometimes fault gets split. In one Seattle sidewalk case, the neighboring owner was found 52 percent at fault because a hedge on their property kept the sidewalk slick with moss and algae. Washington lets a jury divide fault between everyone who contributed, which is why we look at every party, not just the obvious one. Homes, Rentals, Businesses and Bus Stops: Who Pays Depends on Where You Slipped I won’t say “public sidewalk means city, private property means owner” and stop there. Real falls don’t fit that neatly. So let’s go by location. Slipping in Front of a House or Rental in West Seattle: Owner or Tenant? West Seattle has some of the steepest residential streets in the city. Admiral, the hills above Alki, the north facing blocks that never see sun in January. Ice on those slopes can sit for days after the rest of the city has thawed. If you fell in front of an owner occupied home, the owner is usually the starting point. If it’s a rental, things get interesting. The code says “owner or occupant,” and many leases assign snow and ice removal to the tenant. In practice, we often look at both, and the lease decides a lot. You’re almost never collecting from your neighbor’s savings account. Homeowners and renters policies usually include liability coverage, and that’s what pays these claims. I bring this up because a lot of people hesitate to call me. They don’t want to “sue the nice lady down the street.” That’s understandable. But in most cases you’re dealing with her insurance company, not her. Falling at a Store Entrance or Apartment Common Area Businesses owe a higher level of care to customers than a homeowner owes to someone walking past. A store has to take reasonable steps to find and fix hazards in places customers are expected to walk, like the entrance, the parking lot, and the path from the bus stop to the door. Apartment complexes are similar for common areas. Shared stairs, walkways, and parking lots are the landlord’s responsibility to keep reasonably safe, even when ice forms naturally. Washington courts have rejected the idea that ice is just an “act of God” that nobody has to deal with. If the property owner controls the area and had time to salt it or close it off, they can be responsible. So if you slipped on the steps outside your own apartment building in White Center or Burien, don’t assume it was just bad luck. It might be a claim. How to Build a Winter Slip and Fall Claim in Washington Before the Ice Melts This is the part that frustrates me most. Strong cases get weak because the evidence literally melts. By the time someone calls me a week later, the ice is gone, the owner has salted everything, and it’s their word against yours. The Evidence That Disappears After the First Thaw If you can do it safely, or if someone can do it for you, here’s what matters: Take photos of the exact spot from close up and from far away. The wide shot should show the house number or storefront so nobody can argue about the location. Get a shot that shows how thick the ice is and whether there’s any salt or sand on it. Write down the time you fell and what the weather had been doing. Was it snowing that morning, or had the ice been there for days? Public weather records
Landslide or Fallen Tree Damaged Your West Seattle Home? How Liability Works Between Neighbors
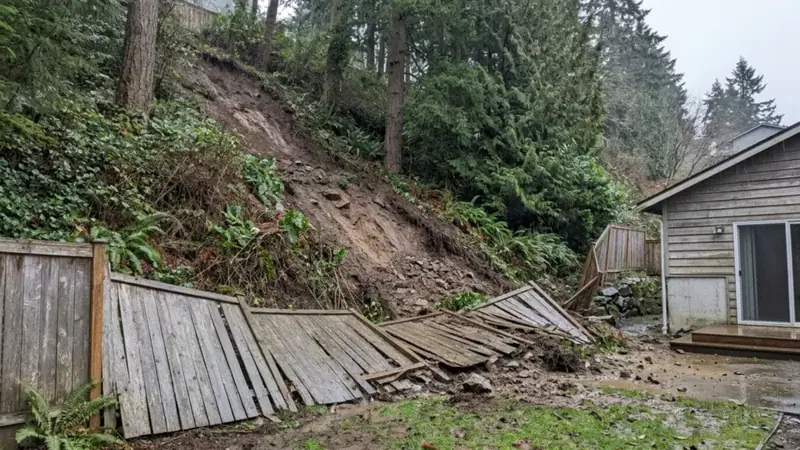
It usually happens at night. Heavy rain for three days, a strange groaning sound, and by morning there’s mud against your back door and a section of fence lying in the yard. Then your insurance company tells you earth movement isn’t covered. Now the real question hits: is this just bad luck, or did your neighbor cause it? In Washington, each owner usually covers damage on their own land. But that changes when someone else’s actions set the slope moving. When Is Your Neighbor Liable for a Landslide on Your West Seattle Property? West Seattle has a long history with slides. The winter of 1996 to 1997 brought hundreds of landslides across the city, and West Seattle was near the top of the list. Seattle’s own emergency planners say winter and early spring are when most slides happen, because the soil is saturated and has nowhere left to put the water. So when your yard moves in January, the timing alone doesn’t tell you much. What matters is why it moved. Why Seattle Law Starts With Each Owner Covering Their Own Land The City of Seattle’s own guidance is pretty blunt about this. Private owners are typically responsible for landslide damage on their own property, unless they can show another party is responsible. Read that second half again. That’s where your case lives or dies. If the slope above you failed purely because of rain and geology, there’s often no one to hold responsible. That’s hard to hear. But if your neighbor did something that made the slope less stable, the picture changes completely. It also helps to know whether your street sits in a mapped slide area. Seattle maps steep slopes and known landslide prone areas under its environmentally critical areas rules, and a big share of those areas are zoned for single family homes. Being on the map doesn’t prove anyone did anything wrong. But it does mean the risk was knowable. An owner building, grading or draining water on a mapped slope is expected to take that risk seriously, and the city’s own policy has long said private owners carry responsibility for risks to adjacent property, not just their own. The Neighbor Actions That Shift Liability Uphill: Drainage, Fill and Grading Before law school I worked as a geotechnical engineer on projects around Puget Sound. A lot of that job was figuring out why slopes fail. And here’s what I learned: in residential neighborhoods, the cause is very often water that somebody put somewhere it shouldn’t be. These are the things I look for first: If your uphill neighbor did any of these, and especially if they knew the slope had moved before, you may have a real claim against them. How to Prove a Slide Was Not Just Bad Weather This is where most landslide claims get stuck. Everyone agrees it rained a lot. Everyone agrees the hill came down. The fight is over cause, and that’s an engineering question before it’s a legal one. What a Geotechnical Report Shows That Photos Cannot Photos show you the damage. A geotechnical investigation shows you the mechanism. It looks at soil layers, groundwater, where the failure surface started, and how water was moving through the slope. That’s the evidence that can connect a slide to a neighbor’s drainage pipe instead of to the weather. Here’s what I’d tell any client. Don’t rush out and pay for a full report on day one. I can usually look at what you already have, photos, the city inspection notes, any old reports from when the house was bought, and tell you whether a full engineering study is worth the money. Sometimes it is. Sometimes the facts make it obvious the slope failed on its own, and I’d rather you know that before spending thousands. Signs the Slope Was Moving Before This Winter Slopes usually give warnings. Cracks in a driveway that slowly widened. A fence that started leaning a few years ago. Doors that began to stick. Trees with trunks that curve at the base. A retaining wall bulging outward. If your neighbor saw those signs and did nothing, or made things worse, that knowledge matters. Washington property owners are expected to deal with risks they know about on their own land, especially risks to the people below them. Old emails, conversations with the neighbor, even a listing description from when the house sold can help show what they knew. In the first days after a slide, a few things protect both your safety and your claim. If the house itself moved, cracked or lost support, stay out and call the city. Seattle inspects private property damaged by landslides, and that inspection report becomes part of the record. Photograph everything before any cleanup starts: the slide scar, where water was flowing, any pipes or downspouts near the top, the fence lines, and the neighbor’s yard if you can see it from your property. Write down the date and time you first noticed movement and what the weather had been doing that week. And keep talking to your neighbor, but keep it calm and factual. Say what you saw, not who you think is to blame. Those early conversations often get repeated later, and you want yours to sound reasonable. Paying for the Damage When Insurance Says No Let’s talk about money, because that’s what keeps people up at night after a slide. Why Most Seattle Homeowners Policies Exclude Earth Movement Standard homeowners policies usually exclude earth movement, which includes landslides and mudflows. Seattle’s own emergency managers have warned residents about this for years. Separate landslide coverage exists, but most people don’t carry it. There’s one important wrinkle. Some policies cover damage when another covered cause, like a burst pipe, triggers the movement. Read your denial letter closely and don’t assume it’s the final word. And if your neighbor’s actions caused the slide, their liability coverage may respond even when your own policy won’t. A fallen tree works a bit differently.
Found an Old Heating Oil Tank Under Your Seattle Home? What It Means for Your Sale or Purchase
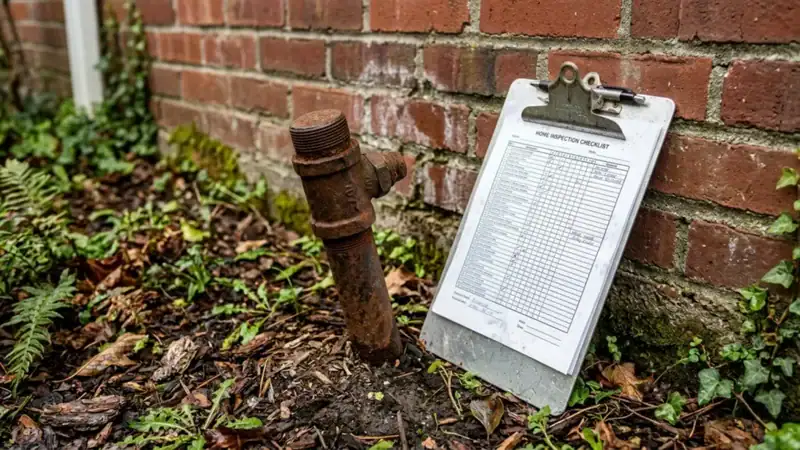
The inspection was going fine. Then the inspector pointed at a small pipe sticking out of the ground near the foundation and said, “That’s an oil fill. There may be a tank down there”. Suddenly the house you loved, or the sale you’d planned around, has an unknown attached to it. A buried oil tank is common in older Seattle homes and is usually manageable. But a decommissioned tank isn’t proof that the soil is clean, and the contract decides who pays if it isn’t. What a Buried Oil Tank Really Means for a Seattle Home Sale A huge share of Seattle homes built before the 1970s heated with oil at some point. Walk through Beacon Hill, West Seattle or Georgetown and you’ll see fill pipes and vent pipes on houses that switched to gas or electric decades ago. Most of those owners never thought about the tank again. That’s the problem. A tank nobody thought about for 40 years is a tank nobody checked for 40 years. Decommissioned Versus Clean: Why They Are Not the Same Thing I studied environmental engineering before I went to law school, and this is the point I wish every buyer and seller understood. Decommissioning is about the tank. It usually means the oil was pumped out and the tank was either removed or filled with an inert material like sand or foam and left in place. When it’s done properly, the tank itself stops being a risk. Clean is about the soil. If that tank leaked before it was decommissioned, maybe years before, the oil may already be in the ground around it. A certificate that the tank was decommissioned says nothing about whether the soil was tested, or what the results were. So when a seller hands you a decommissioning certificate and says “it’s handled,” the honest response is, “Okay, but was the soil tested, and can I see the results?” Soil testing isn’t mysterious. A contractor takes samples from the ground around and below the tank, and a lab checks them for petroleum. The results get compared to Washington’s cleanup standards. If the numbers come back under those levels, you’re in good shape. If they don’t, you know you’re dealing with a cleanup, and you know it before you own it. That’s the whole point. You want the bad news while you can still negotiate. Records You Can Check Before You Negotiate You don’t have to guess about everything. In Seattle, decommissioning work generally goes through the fire department, which keeps records by address. Ask the seller for any paperwork, then check whether the city has a record that matches. When you ask the seller for paperwork, be specific. Ask for the decommissioning report, the name of the contractor who did the work, the date it was done, any soil sample results, and whether the tank was ever registered with the state’s heating oil insurance program. “We think the previous owner took care of it” isn’t an answer. It’s a guess. It’s also worth asking a tank locating company to scan the yard. Some older homes had more than one tank, and I’ve seen cases where an above ground tank was in use while an older buried one sat forgotten in the side yard. If there was ever an oil furnace, assume there might be a tank until someone proves there isn’t. Who Pays for an Oil Tank in a Washington Real Estate Deal? There’s no automatic rule that says the seller always pays or the buyer always pays. It’s negotiated. And the way it’s negotiated decides who carries the risk after closing. Seller Disclosure Duties on Form 17 Washington requires most residential sellers to fill out a disclosure statement, called Form 17, and it asks about environmental issues including storage tanks. If a seller knows about a tank, they have to say so. Here’s why that matters to sellers: honest disclosure protects you. A seller who discloses a tank and what they know about its condition is in a much stronger position later than a seller who checks “no” and hopes nobody digs. And to buyers: if you find a tank the seller clearly knew about but didn’t disclose, that can give you options even after closing. This is also where sellers of inherited homes get caught. If you’re selling your parents’ house in Beacon Hill or Georgetown, you may honestly have no idea whether there’s a tank. That’s fine, as long as your disclosure says so. Then consider a quick tank scan before listing. It costs far less than a deal collapsing three weeks into escrow because a buyer’s inspector found a fill pipe nobody mentioned. Sellers, if you’re not sure whether there’s a tank, say that. “Unknown” is better than a confident “no” you can’t back up. Credits, Price Cuts and Seller Cleanup: Which Protects You Most When a tank turns up, deals usually go one of three ways. The seller decommissions the tank, and sometimes tests the soil, before closing. This is often the cleanest option for a buyer, as long as the work is done by a licensed contractor and the soil results come back in writing before you close. The seller gives a credit at closing and the buyer handles it after. This is popular because it keeps the deal moving. But here’s the catch I always point out. A credit is a fixed number. If the tank is clean, great. If the soil is contaminated, the cleanup could cost far more than the credit, and now that’s your problem. The parties cut the price. Same issue as a credit. You’ve traded an unknown risk for a known discount, and that only works if the discount is big enough. Timing matters here too. Most Seattle purchase agreements give the buyer a limited inspection window. If a tank turns up on day four of a ten day window, there may not be time to scan the yard, pull samples and get lab results back. That’s
Hit by a Car While Walking in West Seattle After Dark: What Changes About Your Claim
It was barely 5:30, but it was already pitch black and raining sideways on Delridge. You stepped off the curb, and the next thing you remember is the hood of a car. A few days later the driver’s insurance adjuster calls, sounding friendly, and asks what you were wearing. That question isn’t small talk. But walking at night doesn’t cancel your claim in Washington. But it does give the insurer an argument, and you need to know how to answer it. Does Walking at Night Hurt Your Pedestrian Claim in Washington? West Seattle in December and January is dark by late afternoon, wet most days, and full of commuters in a hurry. The headlights reflect off wet pavement, wipers are going, and people in dark rain jackets blend right into the background. Insurers know all of this. And they’ll use it. How Comparative Fault Works When You Were Hard to See Washington follows a rule called pure comparative fault. It means fault can be divided between everyone involved, and your recovery is reduced by your share. It doesn’t disappear. Here’s a simple example. Say your total damages, medical bills, lost wages, pain, come to $100,000. If a jury decides you were 20 percent at fault for crossing where you did in dark clothing, you’d recover $80,000. Even if you were found more at fault than the driver, you could still recover something under Washington’s rule. So when an adjuster hints that it was “your fault for walking in the dark,” what they’re really doing is negotiating a percentage. And percentages can be argued. The arguments tend to repeat. You were wearing dark clothes. You were looking at your phone. You crossed mid block instead of at the corner. You stepped out from between parked cars. You’d had a drink with dinner. Some of those may be partly true. That’s okay. A small share of fault on your side doesn’t erase a driver who was speeding, distracted, or simply not looking. The fight is over how big each share is, and that’s decided by evidence, not by whoever sounds most confident on the phone. Why Drivers Must Drive for Dark, Wet Seattle Conditions Too This is the part insurers leave out. Darkness and rain don’t only put duties on pedestrians. They put duties on drivers too. A driver in Washington has to use reasonable care for the conditions. That means slowing down when visibility is poor, keeping headlights on and working, keeping their eyes on the road instead of their phone, and watching for people at intersections and bus stops. A driver who’s going the speed limit on a rainy night when nobody could see 50 feet ahead may not be driving reasonably at all. Turning drivers are a big part of this. A lot of pedestrian crashes happen when a driver turns at an intersection, looks left for a gap in traffic, and never looks right at the crosswalk they’re about to drive through. In the dark, with rain on the windshield, that habit is even more dangerous. Bus stops are another hot spot. People step off a bus, walk around the front of it, and a driver passing the stopped bus never slows down. So the question isn’t only “could the driver see you?” It’s “should a careful driver have been going slowly enough and paying close enough attention to see you?” That’s a very different question, and it often shifts fault back toward the driver. Proving the Driver Should Have Seen You on a West Seattle Street This is where pedestrian cases are won or lost. And most of the evidence has a short shelf life. Street Lighting, Speed and Headlight Evidence Start with where it happened. Was there a streetlight on that corner, and was it working? Was it a marked crosswalk or an intersection without paint? Here’s something that surprises a lot of people. In Washington, most intersections have crosswalks even when there are no painted lines. The law treats the extension of the sidewalk across the road at an intersection as an unmarked crosswalk. So if you crossed at the corner of California Ave SW and a side street with no paint, you may well have been in a legal crosswalk, and drivers had to yield. Get the police report number if officers came to the scene, and read the report as soon as it’s available. Reports sometimes include the driver’s first explanation, which can be very different from what they say a month later. “I didn’t see her until the last second” is a statement worth having in writing. If no officer came, write your own account while it’s fresh: where you started crossing, which way you looked, where the car came from, and what the driver said afterward. Then look at the driver. How fast were they going? Were their headlights on, and were both working? Were they turning, and looking left for cars instead of right for people? Phone records, vehicle data and damage patterns on the car can all help tell that story. Finding Bus, Business and Doorbell Video Before It Is Erased This is my biggest piece of practical advice. Video disappears fast. King County Metro buses have cameras. Businesses along Delridge, California Ave, 35th Ave SW and around White Center have security cameras. And these days half the houses on any block have doorbell cameras pointed at the street. Most of these systems record over themselves within days or weeks. If someone can walk the area in the first few days and politely ask nearby homes and businesses to save footage from that time, do it. Write down which buildings have cameras, even if they say no. A formal request can come later, but only if the footage still exists. Video is often the single piece of evidence that ends the “you came out of nowhere” argument. My post on what evidence strengthens a personal injury case in West Seattle covers the rest of what’s worth gathering. Who
Washington Estate Tax Changed Again in July 2026: Does Your Seattle Estate Plan Still Work?
If you’ve tried to keep up with Washington’s estate tax lately, I don’t blame you for giving up. The rules changed in July 2025, then changed again in July 2026. Here’s where things stand now. For deaths on or after July 1, 2026, Washington taxes estates above $3 million, with rates back to the older range of 10 to 20 percent. That $3 million line is now effectively frozen. And for a lot of ordinary Seattle families, that’s closer than it sounds. Washington Estate Tax in 2026: What Changed on July 1 Washington is one of the few states with its own estate tax, and it kicks in far below the federal level. In 2026 the federal exemption is $15 million per person. Washington’s is $3 million. So plenty of families who will never owe a cent of federal estate tax can still owe Washington. Three Rule Sets in Two Years, Explained Simply Here’s the timeline. To put the rate change in perspective, Beresford Booth, a Washington law firm, ran the numbers on an $8 million estate. Under the July 2025 to June 2026 rates, the Washington tax came to about $840,000. Under the rates in effect from July 2026, it drops to about $730,000. That’s real money, but notice what didn’t change: both estates still owe a large bill, because both are well over the $3 million line. Which set applies depends on the date of death, not the date the will was signed. That matters for anyone handling an estate right now, and it matters for anyone whose plan was built around one particular year’s rules. Why the $3 Million Exclusion Is Now Frozen The new law ties future inflation adjustments to a regional price index that no longer exists. In practice, that means the $3 million exclusion isn’t going to grow on its own. Some estate planners expect lawmakers to revisit this in 2027, but nobody can promise that. Think about what that means in Seattle. Home values tend to climb. Retirement accounts grow. The line stays put. Every year a frozen exclusion stays in place, more middle class families drift toward it without changing anything about how they live. Will Your Seattle Family Owe Washington Estate Tax? Let’s look at an ordinary picture. How a West Seattle House and Retirement Accounts Add Up Picture a retired couple in West Seattle. They bought their house decades ago, and it’s worth well over a million dollars today. They each have retirement accounts. There’s a modest brokerage account, a car, and some savings. Nobody would call them rich. But add it up and they can be surprisingly close to $3 million. And here’s the part couples often miss. Washington doesn’t let a surviving spouse automatically use the unused exclusion of the spouse who died first. Under federal law that’s possible. Under Washington law it isn’t. So without planning, a couple can end up using only one $3 million exclusion instead of two. Here’s how that plays out. Say the first spouse dies and leaves everything outright to the survivor. No tax is due then, because property passing to a spouse is generally deductible. But when the survivor dies years later, the whole combined estate is taxed with only one $3 million exclusion. Half the couple’s tax protection simply disappeared. That’s the kind of thing a well drafted plan can address. A plan that just says “everything to my spouse” may waste the first spouse’s exclusion entirely. Life Insurance and Other Assets People Forget to Count When people estimate their estate, they usually count the house and the bank accounts and stop. But the Washington taxable estate is calculated a lot like the federal one, which means more things count than people expect. Life insurance you own on your own life generally counts at its death benefit, not its cash value. A $1 million term policy you barely think about can push an estate over the line by itself. Retirement accounts count at their full value, even though your kids will owe income tax when they withdraw the money later. Your share of a business, rental property or vacation cabin counts too, and those can be hard to value. If you’ve never added all of this up on one page, it’s worth doing. Honestly, the number surprises people more often than not. There’s one bit of good news hidden in Washington’s rules. Washington doesn’t have its own gift tax. That means money or property you give away during your life generally isn’t part of your Washington estate when you die, as long as it’s really given away. For some families, steady gifts to children or grandchildren over several years can bring an estate back under the line. It’s not right for everyone. You don’t want to give away money you might need for care later. But it’s a tool a lot of people don’t know they have. And if you’re married, there’s a newer rule worth knowing. Since January 2025, a married person’s home can be left out when deciding whether a Washington estate tax return even needs to be filed after the first spouse dies. That helps with paperwork. It doesn’t remove the home from the estate for tax purposes later, so don’t read it as a loophole. Signs Your Washington Will or Trust Needs an Update Not every plan needs to change because of SB 6347. But some definitely do. Here’s what I’d look for. Formula Clauses Written for Old Exemption Amounts Many trusts and wills don’t name a dollar amount. Instead they use a formula, something like “the maximum amount that can pass free of estate tax goes into this trust, and the rest goes to my spouse”. That sounds smart, and it often is. But when the exemption amount jumps or freezes, the formula can push more or less money into a trust than you intended. If your plan includes a credit shelter trust, a bypass trust, or a disclaimer trust, it was probably built
Your Business Partner Wants Out: How LLC Buyouts Work in Washington Without a Clear Operating Agreement
It usually starts with a coffee that feels a little too serious. Your partner says they’re done, they want to move on, and they’d like to “work something out”. Then you go looking for the operating agreement and realize you never really had one. Maybe there’s a template from the formation website. Maybe there’s nothing. But in Washington, a partner leaving doesn’t automatically mean they get bought out, and it doesn’t automatically mean they stop sharing profits. That second part is what catches people. What Happens When a Member Leaves a Washington LLC With No Operating Agreement? When an LLC has no written agreement, Washington’s Limited Liability Company Act fills the gaps with default rules. Those defaults were written to be fair in a general sense. They weren’t written with your two person landscaping company in Tukwila or your three owner coffee shop in West Seattle in mind. Before assuming you have nothing in writing, look harder. Emails where you agreed on a 60/40 split. Texts about who would put in how much money. The tax returns your accountant filed, which usually show each owner’s percentage on their K-1. A bank loan application where you both listed your ownership. None of these is a full operating agreement, but they can show what you actually agreed to, and that can matter a great deal when you’re working out a price. Leaving the LLC Versus Selling the Share People mix these up all the time, and the difference matters. Leaving, which the law calls dissociation or withdrawal, is about your role. When a member is dissociated, they generally lose the right to vote, manage, and make decisions for the company. Selling the share is about money. Your ownership stake, what the law calls a transferable interest, is the right to receive distributions and a share of what’s left if the company winds down. Under Washington’s defaults, those two things can separate. A partner can stop being a member but still hold the economic interest. And Washington’s Act doesn’t give the remaining owners a right to kick someone out, or give the departing owner a right to force the others to buy them out, unless an agreement says so. Why a Departing Partner Can Still Collect Profits Here’s the scenario I see most often. One partner walks away from the day to day work. The other keeps running the business, working longer hours, growing it. Two years later, the business is doing well, and the partner who left still has a claim to their share of distributions. That feels deeply unfair to the person still working. But without an agreement that says otherwise, the departing partner’s economic stake doesn’t just vanish because they stopped showing up. So the real goal of a buyout isn’t only to get someone out of the room. It’s to cleanly buy that economic interest so the business stops owing them anything going forward. Until that happens, you’re running a company with a silent partner you didn’t choose. How to Structure an LLC Buyout in Washington That Holds Up Once both sides agree the remaining owners will buy out the departing one, the work becomes very practical. Two questions drive everything: what is the share worth, and how does it get paid? Agreeing on a Fair Value for a Small Business Share There’s no single right number. With a small private business, value is usually a negotiation backed by some reasonable method. Some owners agree on a simple formula, like a multiple of average annual profit over the last few years. Others look at asset value, which works better for businesses with equipment, inventory or real estate. For bigger or more complicated businesses, a professional valuation can be worth the cost, especially if the two of you already distrust each other’s numbers. My advice is to agree on the method before anyone argues about the number. It’s much easier to say “we’ll use the last three years of tax returns” than to fight over whether the business is worth $200,000 or $400,000. Be honest about what each partner actually brought. One may have put in most of the startup cash. The other may have brought the client list, the license, or years of unpaid evenings. Those contributions don’t automatically change the legal ownership split, but they often shape what feels fair, and a deal that feels fair is a deal that sticks. Also, don’t forget debts. If the departing partner personally guaranteed a business loan or a commercial lease, they’ll want off that guarantee as part of the deal. Lenders and landlords have to agree to that, so plan for it early. Paying Over Time Without Losing Control Most small business owners don’t have the cash to buy out a partner in one lump sum. That’s normal. Buyouts are often paid over time through a promissory note. But a payment plan needs guardrails on both sides. The departing partner wants security in case payments stop. The remaining owners want the departing partner fully out of management on day one, not hovering until the last payment. A well written purchase agreement handles both. It transfers the full interest at closing, sets the payment schedule, says what happens if a payment is late, and includes releases so neither side can come back later with old claims. The agreement should also deal with the things that walk out the door with a person. Who keeps which clients? Can the departing partner contact them? What happens to the company’s passwords, social media accounts, phone number, and customer list? Washington limits how far a noncompete can reach, so if you’re hoping to keep a former partner from competing, get advice on what will actually hold up rather than copying a clause from the internet. Confidentiality and non solicitation terms are often more realistic. Talk to your accountant before you sign, too. How the buyout is structured, whether the company buys the interest or the remaining owners buy it personally, can change the tax
Washington Now Taxes Advertising and IT Services: Do Your Client Contracts Need Rewriting Before Renewal?
You run a small agency, an IT support shop, or a web development studio. Renewal season is coming, and you pull up last year’s client agreement. The price is right there: a flat monthly fee. The word “tax” appears nowhere. Since October 1, 2025, Washington has charged retail sales tax on many of these services. So here’s the question nobody answered for you: if the contract says nothing, who pays that tax? Often, if you don’t sort it out in writing, the answer ends up being you. Which Seattle Service Businesses Now Charge Washington Sales Tax? For decades, Washington’s sales tax mostly hit goods, plus a narrow list of services. A law called ESSB 5814 changed that. It took effect October 1, 2025, and moved a long list of business services into the sales tax base. Advertising, IT, Web Development and Other Services Under ESSB 5814 According to the Washington Department of Revenue, the services now subject to retail sales tax include: If you’re a marketing consultant, an IT managed service provider, a web designer or a freelance trainer, there’s a good chance at least part of what you sell is now taxable. And it cuts the other way too. Your own costs probably went up. The ad platform you buy space through, the IT company that supports your office, the freelancer who builds landing pages for you may all be adding tax to your bills now. If you resell some of those services to your clients, ask your accountant whether you can buy them for resale instead of paying tax twice. Washington has a reseller permit system for exactly that situation, and the contract with your vendor should reflect it. Services That Are Still Not Taxed, Like Legal and General Consulting Not everything changed. Legal services, accounting, medical services, real estate services and general business consulting generally remain outside retail sales tax. That sounds simple until you look at what many small businesses actually sell. A “growth consultant” might give general strategy advice, which isn’t taxable, and also run paid ad campaigns, which is. An IT firm might bundle general business advice with network support. When one contract mixes taxable and non taxable work at a single price, it gets messy fast. And messy contracts are where tax disputes start. Who Pays the New Sales Tax When Your Contract Is Silent? Tax Inclusive Versus Tax Exclusive Pricing Language Under Washington law, sales tax is meant to be collected by the seller from the buyer. But the Department of Revenue generally looks to the seller to make sure it gets paid. If you don’t collect it, the state can still come to you for it. Now picture your contract. It says $3,000 per month for digital marketing services. Nothing about tax. You start adding sales tax to the invoice, and the client says, “Our contract says $3,000. That’s what we agreed to.” Who’s right? That’s exactly the kind of argument that turns a good client relationship sour. A contract that clearly says prices are “exclusive of applicable taxes, which the client will pay” heads off the whole fight. A contract that says nothing leaves you arguing, and possibly paying the tax out of your own margin. Here’s the simple math. On a $3,000 monthly retainer, the sales tax in a Seattle area location adds up to thousands of dollars a year. If you end up absorbing that, it comes straight out of your profit. Why Changing an Old Contract Can Trigger the Tax When the law took effect, the Department of Revenue issued guidance for contracts signed before October 1, 2025. Some of those older agreements got temporary relief. That relief had limits, and for many services it has since run out. Watch for automatic renewals as well. A lot of small service contracts roll over every year unless someone cancels. If yours does, there may never be a moment where you sit down and sign a new version, which means the old silent pricing language just keeps rolling forward. Don’t let a contract you set up years ago decide who pays a tax that didn’t exist when you wrote it. Here’s the trap. The guidance said that if an existing contract is materially changed after October 1, 2025, the tax applies from the date of the change. So a renewal, a price change, or a new scope of work isn’t just a business update. It can be the moment your old tax treatment ends. If January is when you renew, January is when you need the right language in place. Contract Clauses to Update Before Your Next Renewal I’d rather you spend an hour fixing your template now than spend months arguing with a client later. These are the pieces I look at first. A Clear Sales Tax Clause for Service Agreements At minimum, your agreement should say three things. That stated prices exclude sales tax and other applicable taxes. That the client is responsible for paying those taxes on top of the stated price. And that if tax law changes during the contract, the tax will be adjusted to match the law. It also helps to say where the service is considered delivered, because that affects which local rate applies. If you have clients outside Washington, or clients with offices in several cities, the sourcing rules can change what you charge. That’s worth sorting out with your accountant, and the contract should match whatever approach you settle on. Think about clients who claim they shouldn’t be charged at all. Some buyers may be exempt, or may be buying your service to resell it. The contract can say that the client must give you any exemption or resale paperwork up front, and that if the state later disagrees, the client covers the tax. That one sentence moves the risk to the party making the claim. Then make sure your invoices match your contract. If the agreement says tax is separate and your invoice shows one bundled number, you’ve
Do You Need a Probate Lawyer in Seattle? When an Estate Actually Requires One
Not every estate in Washington needs to go through probate, but more do than people expect, especially once real estate is involved. Probate is generally required when the deceased owned real property titled in their name alone, or when the total estate is worth $100,000 or more. Below that, and without real estate, Washington’s small estate affidavit often lets you skip probate entirely. The wrong guess in either direction costs you, either in wasted legal fees or in a frozen estate you can’t actually settle. The Real Test: Does Your Situation Actually Require Probate in Washington Here’s the actual test, in the order that matters most for a typical West Seattle estate. If the Estate Includes a Home or Other Real Estate Titled Solely in Their Name If your loved one owned a house, condo, or any real property with only their name on the title, that alone almost always triggers probate. Real estate can’t legally change hands without either a probate court appointing someone with authority to sign the deed, or the property having been set up ahead of time to avoid probate, through a trust or joint ownership with right of survivorship. This is the detail that catches a lot of West Seattle families off guard. Home values here mean even a modest single-family house, owned outright with no other significant assets, is usually enough on its own to require probate. The question isn’t really whether the estate has enough assets, it’s whether there’s a house with only one name on the title. That’s exactly the kind of situation Pathfinder’s probate and estate team handles regularly for West Seattle families. If there’s no will, this gets more complicated rather than less. Washington’s intestacy laws determine who inherits, and who has priority to serve as personal representative, based on a specific order of relatives. A surviving spouse, adult children, and other relatives each have a legal right to petition the court in a particular sequence, which sometimes creates disagreement about who should be in charge, especially in blended families. Probate resolves that question with actual legal authority; an informal family agreement does not. If the Estate’s Total Value Is Near or Above $100,000 Real estate aside, Washington also requires probate once an estate’s total value crosses roughly $100,000. That number includes bank accounts, vehicles, and personal property, but it excludes assets that already have a named beneficiary, like a life insurance policy or a retirement account, since those pass directly to whoever’s listed without going through probate at all. For most families, this threshold ends up being a formality once real estate is in the picture, since a house alone typically clears $100,000 many times over. Where it actually matters is for estates with no real property, where the total might genuinely land under the line, which is exactly the situation the small estate affidavit was built for. Picture a paid-off West Seattle starter home worth $750,000, owned by someone whose only other assets were a checking account and a car. That single house is worth roughly seven times the probate threshold on its own. This is why the real estate question almost always answers the value question at the same time, at least in this market. Some West Seattle estates get more complicated than a single home, particularly if the deceased owned a rental property or held title jointly with a business partner rather than a spouse. Mixed ownership situations like these almost always benefit from a probate attorney’s review early on, since figuring out exactly what portion of a property belongs to the estate can get complicated fast. If you’re unsure after running through these factors, a short conversation with an attorney is usually faster than trying to research every exception yourself, and it costs nothing to find out. What Washington’s Small Estate Affidavit Can (and Can’t) Skip for You If there’s no real estate involved and the estate’s total value stays under the threshold, Washington law allows heirs to collect the deceased’s assets using a small estate affidavit instead of opening a full probate case. You can’t file it immediately, though. The law requires a 40-day waiting period after the date of death before the affidavit can be used. Once that window passes, the affidavit lets you present it directly to a bank, brokerage, or other institution holding the deceased’s assets, and they release the funds to you without a court case ever being filed. It’s faster, cheaper, and skips nearly all the paperwork that comes with a formal probate case. What it can’t do is transfer real estate titled solely in the deceased’s name in most situations, which is why the affidavit only works cleanly when there’s no house or property involved. It also doesn’t resolve disagreements between heirs, something Pathfinder’s civil disputes attorneys see come up more often than people expect, and it doesn’t give you the same formal protection against creditor claims that opening probate does. If there’s any tension among family members about who gets what, or debts you’re not fully sure about, a small estate affidavit can end up creating more problems than it solves. What Happens If You Skip Probate When the Estate Actually Needs It It’s also worth knowing that Washington’s probate process is generally faster and less expensive than what people picture from movies or from other states. Most estates here qualify for what’s called nonintervention authority, which lets the personal representative handle the bulk of the process, selling the house, paying debts, distributing what’s left, without needing a judge to sign off on every individual step. A lot of what makes probate feel intimidating in other states simply doesn’t apply here. Most straightforward Washington probate cases, where there’s a valid will, no disputes, and nonintervention powers granted, wrap up within about six months to a year, largely dictated by the four-month creditor claim window that has to run before the estate can be closed out. That’s a very different picture from the multi-year probate horror stories
Buying or Selling Property in West Seattle? The Legal Steps Most People Skip
Most West Seattle buyers and sellers assume that having a real estate agent and a title company means every legal step is covered. It doesn’t. Agents handle the market side of the deal, and title companies insure against certain defects, but neither one is actually looking out for your legal interests the way an attorney does. The steps people skip most often involve unpermitted additions common in older homes, earnest money disputes when a deal falls apart, and inspection deadlines that quietly waive your rights if you miss them. The Disclosure and Permit Gap Most West Seattle Buyers and Sellers Miss Washington’s Form 17 seller disclosure asks about known defects and past repairs, but it relies entirely on what the seller actually knows and chooses to write down. It doesn’t require anyone to pull permits or verify that work was done legally, which is exactly where problems tend to surface. Unpermitted Additions, ADUs, and DADUs in Older West Seattle Homes West Seattle’s housing stock skews older, and a lot of these homes have finished basements, converted garages, or backyard cottages that were added over the years without going through the city’s permit process. A seller might genuinely believe a space is fine to disclose as-is, not realizing that an unpermitted conversion can affect the home’s legal square footage, its insurability, or even whether the buyer can finance it. Buyers rarely check permit history unless someone tells them to. A quick pull of the property’s permit record against what’s actually built can catch a converted basement bedroom that was never inspected, or a DADU that doesn’t match what the city has on file. This is one of the first things Pathfinder’s real estate attorneys check before a client signs anything. Catching it before closing gives you room to negotiate, or walk away. Catching it after closing means it’s your problem to disclose to the next buyer. An unpermitted conversion isn’t just a disclosure issue, it can directly affect financing. Many lenders won’t count an unpermitted room toward a home’s official square footage or bedroom count, which can throw off the appraisal the buyer’s loan depends on. And homeowners insurance policies sometimes exclude damage to unpermitted structures entirely, something buyers rarely find out until they try to file a claim years later. Checking permit history isn’t complicated once you know where to look. Seattle’s permit records are searchable through the city’s online services portal by address, and comparing what’s on file against what you’re actually walking through takes maybe twenty minutes. It’s a step worth doing before you write an offer, not after. Sellers sometimes push back on disclosing something they didn’t build themselves, assuming a previous owner’s unpermitted work isn’t their problem to flag. Washington’s disclosure law doesn’t work that way. If you know about it, whether you built it or inherited it when you bought the house, it generally needs to be disclosed. Sellers who skip this because they didn’t personally do the work can end up facing a claim from the buyer down the road anyway. Washington’s recent changes to state ADU and DADU law have made it easier to build these units legally, which is good news going forward, but it also means older, informally built versions that predate the new rules don’t automatically become compliant just because the law changed. If a property includes one, it’s worth confirming whether it was built under current permit rules or grandfathered in some other way, since that affects both value and what you’re allowed to do with it. What Happens When Earnest Money or an Inspection Finding Turns Into a Standoff Deals fall apart more often than people expect, and what happens to the earnest money once they do is rarely as simple as whoever’s right gets it back. Deadlines in the Inspection Addendum That Waive Your Rights If You Miss Them The standard NWMLS inspection addendum gives buyers a specific window to respond after an inspection, either accepting the property, requesting repairs, or terminating the agreement. Miss that deadline, even by a day, and you can lose the right to do anything about what the inspection turned up, no matter how serious it was. Once the inspection period opens, buyers typically have a handful of business days, spelled out in the specific addendum used, to pick one of three paths: accept the property as it is, submit a written request for repairs or credits, or terminate the agreement and get the earnest money back. Sellers then have their own response window to accept, reject, or counter a repair request. Each of these steps has its own deadline, and letting any one of them lapse without a response can be treated as accepting the property as is, repairs and all. In a competitive West Seattle market, earnest money deposits often run one to three percent of the purchase price, which on a typical home here can mean tens of thousands of dollars sitting in limbo the moment a deal gets shaky. That’s real money to have tied up while two sides argue over a release form neither one knows how to draft correctly. When a deal does fall through and both sides think they’re entitled to the earnest money, the funds don’t just get released to whoever asks first. Washington requires a mutual release signed by both parties, or a court to decide, before the escrow or title company can hand the money over. This is exactly the kind of standoff Pathfinder’s civil disputes attorneys step in to resolve. Buyers and sellers who don’t know this sometimes sit on frozen earnest money for weeks longer than necessary, simply because nobody drafted the release correctly. What a Real Estate Attorney Catches That Your Title Company Won’t Title insurance protects you financially if a covered defect turns up after closing. It doesn’t negotiate on your behalf, review your specific contract terms, or catch an easement or boundary discrepancy that’s common on older West Seattle lots where property lines were drawn decades
Construction Disputes in Seattle: What to Do When a Contractor Doesn’t Deliver
When a Seattle contractor doesn’t deliver, the fastest path to a resolution depends on what actually went wrong and how much money is involved. Incomplete work, defective work, and a blown deadline are three different legal problems that need different evidence. And two of the most commonly recommended options, small claims court and a bond claim, both have real limits people don’t find out about until they’re already deep into the process: a $10,000 cap with no attorneys allowed, and bond amounts that rarely cover the full damage. What “Doesn’t Deliver” Actually Means Legally, and Why It Changes Your Options People tend to lump every contractor problem into one bucket, but the law treats them differently, and so does the evidence you need to make your case. Incomplete Work vs. Defective Work vs. Missed Deadlines Incomplete work, where the contractor stopped showing up before finishing, is usually the most straightforward to prove. You have a contract describing the scope, and photos or a walkthrough showing what was never done. Defective work is trickier, since it often requires another contractor or an inspector to document what’s wrong and what it will cost to fix, especially if the original contractor disputes that the work is actually substandard. Missed deadlines are their own category, and they only really matter legally if your contract said something about time being critical, or if the delay caused you real financial harm, like extra rent or storage costs. A contract that’s silent on timelines gives you much less to work with if your only complaint is that the job ran long. Whichever category your dispute falls into, the documentation you gather now is what makes or breaks a claim later, whether that’s a bond claim, a demand letter, or a lawsuit. Photograph everything before any repair work starts, save every text and email exchange with the contractor, and get a second, independent opinion in writing if you’re claiming the work is defective rather than just incomplete. A judge or an L&I investigator wasn’t there when the work was done. What you can show them afterward is all they have to go on. Why the Bond Claim and Small Claims Route Rarely Cover the Full Loss Both of these get recommended constantly, and both are worth knowing about, but neither one is the complete answer for most real construction disputes. Washington’s $10,000 Small Claims Cap and the No-Attorney Rule Washington’s small claims court caps individual claims at $10,000, and under state law, attorneys can’t participate in the hearing without the judge’s express permission. For a lot of real remodel or construction disputes, where damages run well past that number, small claims simply isn’t built to handle the case, and if you want legal representation involved, it’s the wrong venue from the start. Say your losses come to $7,500 after a contractor walked off a bathroom remodel. That fits comfortably inside the small claims cap, and since you’re representing yourself anyway under the no-attorney rule, it can be a reasonable path if you’re comfortable presenting your own case. Now say the same walk-off happened on a kitchen addition and your losses are closer to $35,000. Small claims can’t touch that, and you’re looking at district or superior court, where having an attorney actually matters. It’s also worth knowing what a court can and can’t actually give you. Small claims and most civil court judgments award money. They generally can’t force a contractor to come back and finish the job the way you originally wanted. If finishing the work matters more to you than getting money back, that changes which remedy is actually worth pursuing from the start. A bond claim through the contractor’s registration has its own ceiling. Washington requires licensed contractors to carry a bond, but the required amount is often modest relative to what a real project actually costs. If your losses are larger than the bond, a successful claim against it still won’t make you whole. It just recovers part of what you’re owed. What to Do Before You Withhold Payment or File a Claim Before deciding on a strategy, check whether the contractor is actually registered and bonded through the Washington Department of Labor and Industries. An unregistered contractor changes everything, since there’s no bond to claim against, and your realistic path becomes a direct lawsuit rather than an administrative process. This is usually the first thing Pathfinder’s construction law attorneys check when a client comes in with a dispute like this. Washington’s contractor lookup tool shows registration status, active bond and insurance information, and any past violations or complaints filed against a contractor, all searchable by business name or registration number in a few minutes. Running this check isn’t just useful after a dispute starts. Doing it before you hire anyone is one of the simplest ways to avoid ending up in this situation in the first place. Before filing anything formally, a written demand letter laying out exactly what was promised, what was delivered, and what you’re asking for, whether that’s a refund, a repair, or a specific dollar amount, is worth sending first. Contractors sometimes resolve a dispute once they see it in writing from an attorney, simply because it signals you’re serious and organized. It also creates a paper trail showing you tried to resolve things reasonably before escalating, which matters if the case eventually does go to court. Filing a complaint with the Department of Labor and Industries opens an investigation into the contractor’s registration and bonding status, and if they find a violation, that’s what can trigger a claim against the contractor’s bond. It’s not a fast process, and L&I isn’t going to negotiate a settlement on your behalf. Think of it as one piece of a larger strategy rather than the whole solution, especially if you’re also pursuing a bond claim or considering a lawsuit at the same time. Mediation through a local home builders association or a private mediator is worth considering before litigation, especially if